Your fixed-cost ratio is the share of your income committed to recurring bills (rent or mortgage, utilities, insurance, loan payments, subscriptions) before you make a single choice. Keeping it at or below roughly half your income leaves room to save and absorb surprises.
Here’s why it matters. Two neighbours earn the exact same salary. One takes a weekend trip on a whim. The other checks the balance before buying groceries. Income isn’t the difference, and often discipline isn’t either. It’s how much of each paycheque was already promised away before either of them got out of bed. That promised-away share has a name, your fixed-cost ratio, and it quietly caps how much freedom your money buys you.
Budget feel tight for no obvious reason? This is where we’d look first.
What the fixed-cost ratio measures
Your fixed-cost ratio is the portion of income committed to recurring costs you can’t easily change from one month to the next. The formula:
Fixed-cost ratio = recurring committed costs ÷ income
Fixed costs overlap a lot with the needs side of a needs-versus-wants split, but they aren’t the same thing: fixed is about how hard a bill is to change, not whether you need it. They’re the bills that show up on schedule whether you think about them or not:
- Rent or mortgage
- Utilities, phone, and internet
- Insurance premiums
- Loan and car payments
- Subscriptions that renew on their own, including the ones you forgot you had
Say those come to $2,600 and you bring home $4,800. Your ratio is about 54%. Everything past that line, the other 46%, is the only money you actually get to steer.
Why keeping it near half matters
Aim to keep fixed costs at roughly half your income, tops. It traces back to the 50/30/20 rule that Elizabeth Warren and Amelia Warren Tyagi popularized in their 2005 book All Your Worth, which caps needs at 50% of take-home pay. Fifty isn’t sacred. Breathing room is the point.
Picture your budget as a spring. Under 50%, there’s give: a rough month comes along, you pull back on the fun stuff, and the essentials still get paid. Push toward 70% or higher and the spring is wound tight. A slow freelance month, a busted furnace, a rent hike, and there’s no slack left to absorb it. The CFPB’s guidance on creating a budget and sticking with it makes the same point. A plan only works if it has room to bend.
Ever wondered how someone on a six-figure salary ends up living paycheque to paycheque? Often it’s this. Lock up 70% of a big income and you’re left feeling broke on money a spreadsheet calls comfortable.
Why it creeps up so quietly
Nobody signs up for a 70% ratio on purpose. It sneaks in. Netflix adds two bucks. A meditation app you tried once starts billing monthly. You finally pay off the Civic, then fall for a new RAV4. Each one’s too small to argue with, and since they all autopay, you never have a reason to look.
Here’s the trap. The thing that makes fixed costs convenient, that they take care of themselves, is the same thing that makes them risky, since they grow without asking. The fix is simply seeing them. Put every recurring charge on one screen and a slow, invisible drift turns into a choice you can make. Skwad’s recurring bills dashboard does exactly that, with year-over-year comparisons so you can see how far your committed costs have moved.
How the ratio connects to everything else
This number sits upstream of a lot. It caps your savings rate, since you can only save out of income that isn’t already spoken for. It drives your emergency-fund runway, because higher committed costs mean more to cover each month. Its narrower cousin, the one lenders use, is your debt-to-income ratio, which counts only loan payments instead of every recurring bill. Committed costs also slow how fast you pay down debt and build assets, so the ratio quietly shapes your net worth too. And that’s why it feeds straight into your overall financial health score.
Bringing it down is often the best money move you’ve got, because it keeps paying off with zero effort. Cancel one subscription you don’t use or haggle one bill down, and every month after that is a little better. Compare that to white-knuckling your restaurant budget forever. While the ratio shifts, Skwad’s flexible envelope budgeting moves with you to keep the other categories in line.
How Skwad tracks it for you
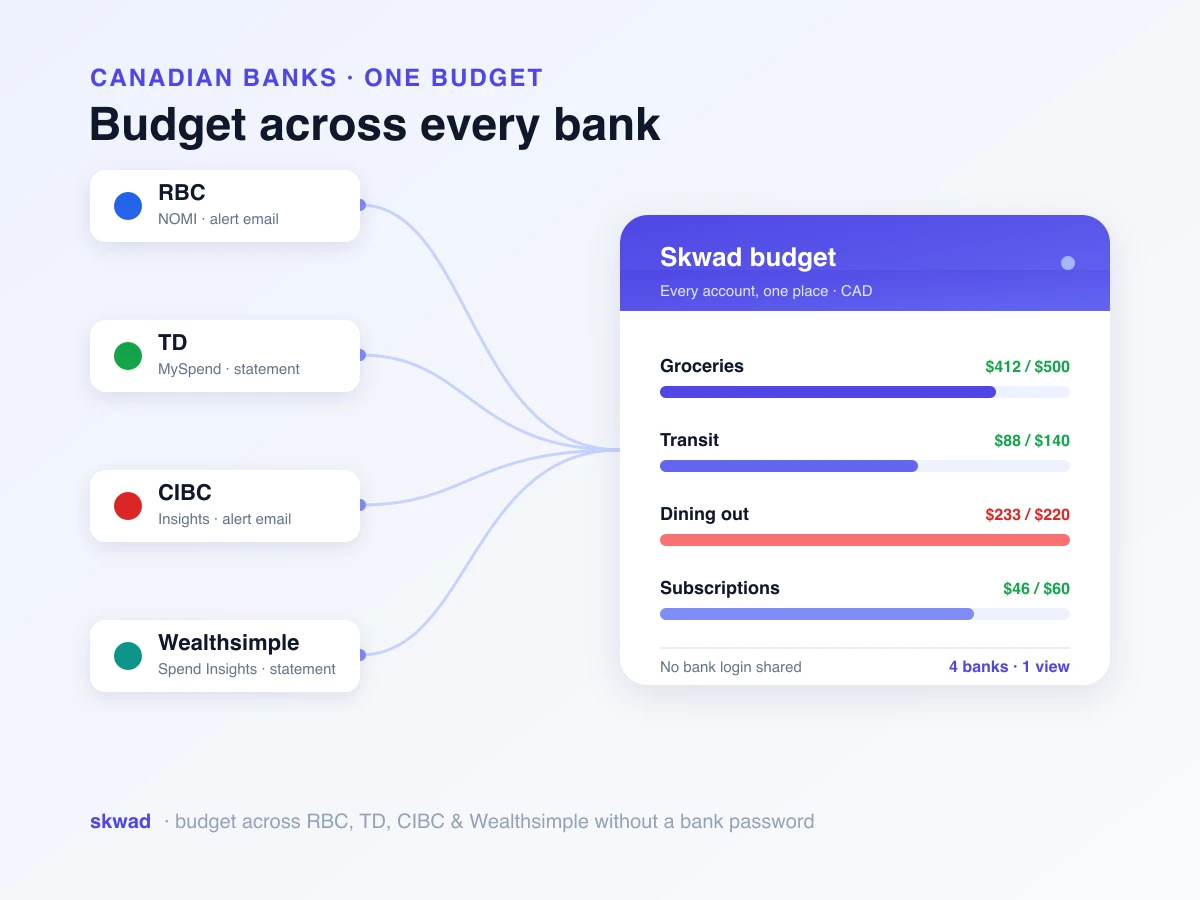
You don’t have to list your bills for us. Skwad picks the recurring ones out of your transaction history on its own, so the ratio updates itself and there’s no monthly tally. We show it in Sight next to your other health signals, and we flag it when committed costs start climbing, so you can do something before a little creep becomes a tight budget.
Frequently asked questions
What is a fixed-cost ratio?
It’s the percentage of your income that your recurring bills (rent, utilities, insurance, loans, subscriptions) claim before you’ve made one decision. High number, little wiggle room. Low number, lots.
What is a healthy fixed-cost ratio?
The common guideline is about half your income, or under. Below that line you can save and still survive a surprise. Up near 70%, one bad month and you’re scrambling, because almost nothing is left uncommitted.
What counts as a fixed cost versus a discretionary one?
If it bills you on a schedule and you can’t just stop it tomorrow (rent, utilities, insurance, phone, internet, loans, subscriptions), it’s fixed. If you choose it fresh every time, like takeout or a new pair of shoes, it’s discretionary. Stuck on something like a gym membership? Ask how painful it would be to cancel by next month.
See what’s already spoken for
Few numbers say more about your money than how much of it is gone before you decide anything. Fewer still get easier to fix the moment you can see them. Open Sight in Skwad to check your fixed-cost ratio, follow its trend, and catch committed costs before they quietly take over.