Your emergency fund should cover about three months of essential expenses, and six months if your income is variable, you’re self-employed, or one earner carries the household. The most useful way to measure it is runway: how many months your savings could cover essentials if the income stopped.
Why months and not dollars? Is $2,000 a good emergency fund? For one person it’s three months of breathing room. For another it’s about eleven days. Same number, completely different safety net, because a dollar figure tells you nothing until you know what your life costs. That’s why we’d rather talk about runway.
So let’s work out your runway, pick a sensible number of months, and talk about why it’s worth checking more than once.
What emergency-fund runway means
Runway is a simple ratio: your accessible savings divided by your essential monthly spending. Grab a napkin. On top, the savings you could pull out tomorrow without a penalty. Underneath, what your essentials cost in a month. Divide.
Say you’ve got $9,000 you can reach and your essentials run $3,000 a month. That’s three months of runway. Bump those essentials to $4,500 and the same $9,000 buys you two. Your balance didn’t move, but you’re less protected, because runway weighs the money against the life it has to carry.
A dollar target can’t do that. Runway stays honest as things change. Get a raise, move into a bigger place, and your savings might grow while your runway actually shrinks. Counting months catches it. Counting dollars doesn’t.
How many months should your emergency fund cover?
We can’t give you a magic number. Your job, your rent, and whether your partner also earns all shift it. Still, there are three well-worn benchmarks.
Three months of essentials is the usual first target, and it’s the reference point in the Consumer Financial Protection Bureau’s guide to building an emergency fund. It covers most short bumps: a late paycheque, a mid-sized car repair, a quiet month if you freelance.
Six months is the sturdier cushion, and it’s worth reaching for if any of these sound like you:
- Your income is variable or seasonal
- You’re self-employed or on contract
- One earner carries the household
- A job search in your field tends to drag on
One month comes before all of that. Zero to one is the jump you feel in your chest. Before it, a surprise bill goes on the credit card. After it, you shrug and pay it.
Don’t let six months scare you off starting. You build runway a month at a time, and the first couple do the most for your nerves.
Base it on essentials, not your whole budget
Here’s a trap we see a lot: sizing the fund against every dollar you spend, concert tickets and all. The target balloons, looks hopeless, and the savings account stays empty.
Think about what would really happen if your income vanished. You’d cut back fast. Streaming, takeout, weekend plans, gone. The number you need is your essential monthly spend: housing, utilities, groceries, insurance, getting around, and minimum debt payments.
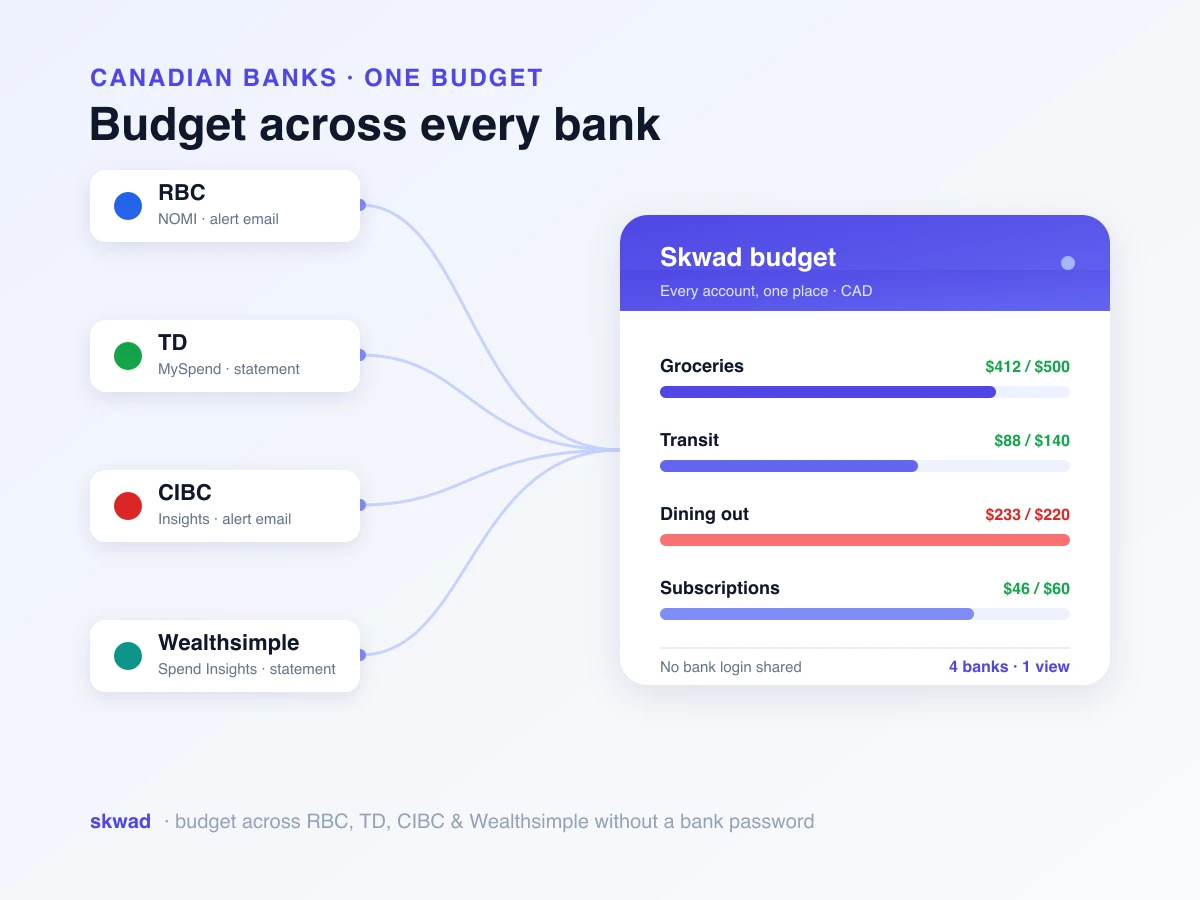
Not sure what your essentials add up to? This is where a proper category breakdown pays for itself. Skwad’s cash flow reports separate the money that has to leave from the money you choose to spend, and that’s the bottom half of your runway math. Knowing which bills are truly locked in (see the fixed-cost ratio guide) makes it sharper still.
Reading runway as an ongoing signal
The usual approach: build the fund, pat yourself on the back, forget about it. The trouble is runway drifts. Rent goes up. A car payment shows up. Groceries creep. The three months you built last year are two months now, and nothing told you.
Drift like that is exactly why a financial health score leans on runway as a core signal. Glance at it monthly. Balance flat but runway sliding? Your essentials quietly got pricier, and now you know.
How fast runway grows depends on your savings rate. Whatever slice of each paycheque you keep is what tops up the pile runway divides. Keep a bigger slice, and each month stretches the runway further.
Skwad Sight works out your runway automatically from the balances you already record. And since you can track balances without linking a bank, you get the whole picture without handing anyone a login.
Frequently asked questions
How many months of expenses should I have saved?
Start by aiming for three months of essentials. Six is the sturdier cushion for freelancers, seasonal workers, and single-income households. Three feels miles away? Get to one. A single month in the bank turns a $900 transmission bill from a crisis into an errand.
How long should an emergency fund last?
Three to six months of essential expenses. Lean toward three if your paycheque is steady, and toward six if your income swings or one earner carries the household.
What counts as an emergency fund?
Cash, basically, sitting in chequing or savings where you can move it today, penalty-free. Stocks you’d need to sell? No. A retirement account with early-withdrawal fees? No. Your credit card limit? Definitely no. If it isn’t there the minute things go sideways, it isn’t the emergency fund.
Should I base my emergency fund on total spending or essential spending?
Essentials. Rent or mortgage, utilities, groceries, insurance, minimum payments, the bus pass or gas. Lose your income and you’d drop the extras within a week, so counting them just makes the goal scarier without making it more accurate.
Know your number of months
“How long could I last?” is a scary question at 2 a.m. and a boring one once you know the answer. We’d like it to be boring for you. Open Sight in Skwad to see your runway today, watch it lengthen as you save, and catch it early if your essentials start outrunning your cushion.