A financial health score is a single number that sums up how well your money is working, built from signals like your savings rate, your fixed-cost ratio, your emergency-fund runway, and whether your net worth is growing. It answers the questions your bank balance can’t.
Check your bank app and you’ll learn exactly one thing: how much is sitting in that account this minute. Nothing about whether you’re saving enough. Nothing about the bills that crept up $40 since spring. Nothing about whether you’d survive a bad month. A score squeezes the answers into one number you can follow over time.
No calculus required, promise.
What a financial health score actually measures
A financial health score is a summary. It blends several separate signals about your money into one number, so a quick look tells you whether things are improving or slipping. Think smoothie: a few readings go in, one number comes out.
Why blend them? Because money trouble rarely shows up in just one spot. Plenty of people save a healthy chunk every month and are still one surprise away from a mess, because their cushion is thin. Others have a fat emergency fund and are still slipping, because fixed bills swallow most of every paycheque. Look at only one of those numbers and you’d miss the other problem completely.
So a decent score watches several things at once. When it moves, that’s your hint to go see which piece moved it.
The signals that feed a good score
Most scores worth trusting chew on a short list of numbers you can actually measure. Each asks you something different.
Savings rate: are you keeping any of it?
Your savings rate is the share of income you keep rather than spend. Income minus spending, divided by income. If you only look at one number to tell whether you’re building wealth or just passing money through, this is it. Around 20% is the figure you’ll hear most, and it’s the savings slice of the 50/30/20 rule Elizabeth Warren and Amelia Warren Tyagi popularized in their 2005 book All Your Worth. Your own target depends on your goals and where you are in life. We go deeper in what your savings rate is and why it matters.
Fixed-cost ratio: how much is already spoken for?
Your fixed-cost ratio is how much of your income is claimed by recurring bills and subscriptions before you choose anything. Once fixed costs pass roughly half your income (the same share 50/30/20 sets aside for needs), there’s not much left to save or to soak up a bad month. It’s one of the sneakiest ways a budget gets tight: no single bill did it, they all did.
Emergency-fund runway: could you cover a rough patch?
Runway is the number of months your liquid savings could cover essentials if your income stopped. About three months is a common first target, which lines up with the Consumer Financial Protection Bureau’s emergency-fund guidance. This is the resilience check, the difference between a setback and a crisis. More on how many months of expenses you should save.
Net worth: is the overall picture growing?
Everything you own, minus everything you owe (here’s what counts toward net worth). One month’s number on its own doesn’t say much. The direction over time does, so the score keeps an eye on whether that line is rising. For the lender’s-eye version, look at your debt-to-income ratio: how much of your income is already spoken for by debt payments.
Why the trend beats the number
Here’s the part people skip. Today’s score matters less than the shape of the line over the last few months.
A 68 by itself tells you almost nothing. Every app scales its score differently, so you can’t even compare across tools. Watching your own score go from 61 to 68 over a quarter, though? That means something real happened: your savings rate went up, fixed costs eased, or the cushion grew. And a score drifting down is the early warning you’d otherwise only get when an account hits zero.
So read it like the check-engine light, not a report card. If it changes, pop the hood and see which metric did it. For the everyday habits that push most of these signals the right way, the Consumer Financial Protection Bureau’s guidance on building and sticking to a budget is a solid primary source.
How Skwad builds your score
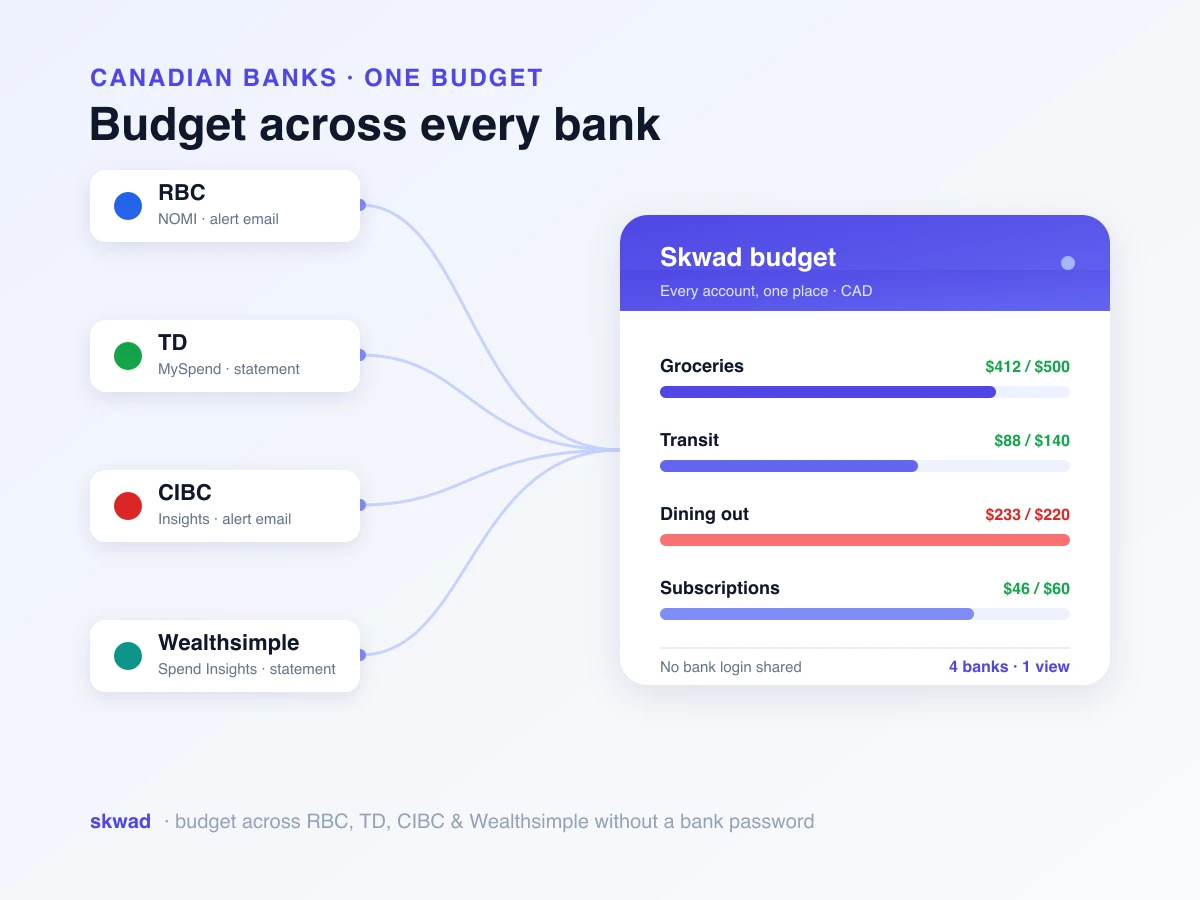
Skwad Sight builds your score from what you already track in Skwad. There’s nothing extra to set up, and you don’t have to link a bank. Forwarded emails, receipt scans, CSV imports, manual entries: Sight reads its signals from any of them. You can track balances without linking a bank and still get the complete score.
Sight scores each signal, combines them, and charts the trend month by month. When one metric is weak, we point at the specific thing to work on instead of leaving you guessing. Want the raw money-in, money-out picture underneath? Skwad’s cash flow reports show exactly that.
Frequently asked questions
What is a good financial health score?
There isn’t one magic number, since every tool scales its score its own way. Watch the direction instead. A score that climbs for a few months running means your savings rate, fixed costs, and cushion are heading the right way. Keep an eye on the trend, and on whichever one or two metrics are pulling it down.
What goes into a financial health score?
Four ingredients show up again and again. How much of your pay you keep (savings rate). How much is gone to bills before you blink (fixed-cost ratio). How many months you could coast on savings (runway). And whether your net worth is inching up. Any one alone has blind spots; together they cover each other.
Do I need to link my bank to get a financial health score?
Not with Skwad. Sight builds your score from the transactions and balances you’re already tracking, whether they came from a bank link, forwarded emails, receipt scans, or typing them in yourself. You can get the full score without ever handing over a bank password.
Start reading your own score
A score won’t fix your finances on its own. What it does is swap that fuzzy “am I doing okay?” feeling for a number you can watch, and point at the one change that would move it most. Open Sight in Skwad to see your score, what’s behind it, and where to focus next.